Credit Score Needed to Buy a House in Florida (2026)
Wondering what credit score you need to buy a house in Florida? Learn how your credit affects mortgage approval, interest rates, and loan options with Nelson Capital Financial Services.
Credit Score Needed to Buy a House in Florida
What Credit Score Do You Need to Buy a Home?
One of the most common questions homebuyers ask is:
“What credit score do I need to buy a house in Florida?”
The answer depends on several factors, including the mortgage program you choose, your income, debt, down payment, and the lender’s underwriting guidelines. At Nelson Capital Financial Services, we help homebuyers throughout Florida understand their credit profile, explore available mortgage options, and take steps toward successful homeownership.
Why Your Credit Score Matters
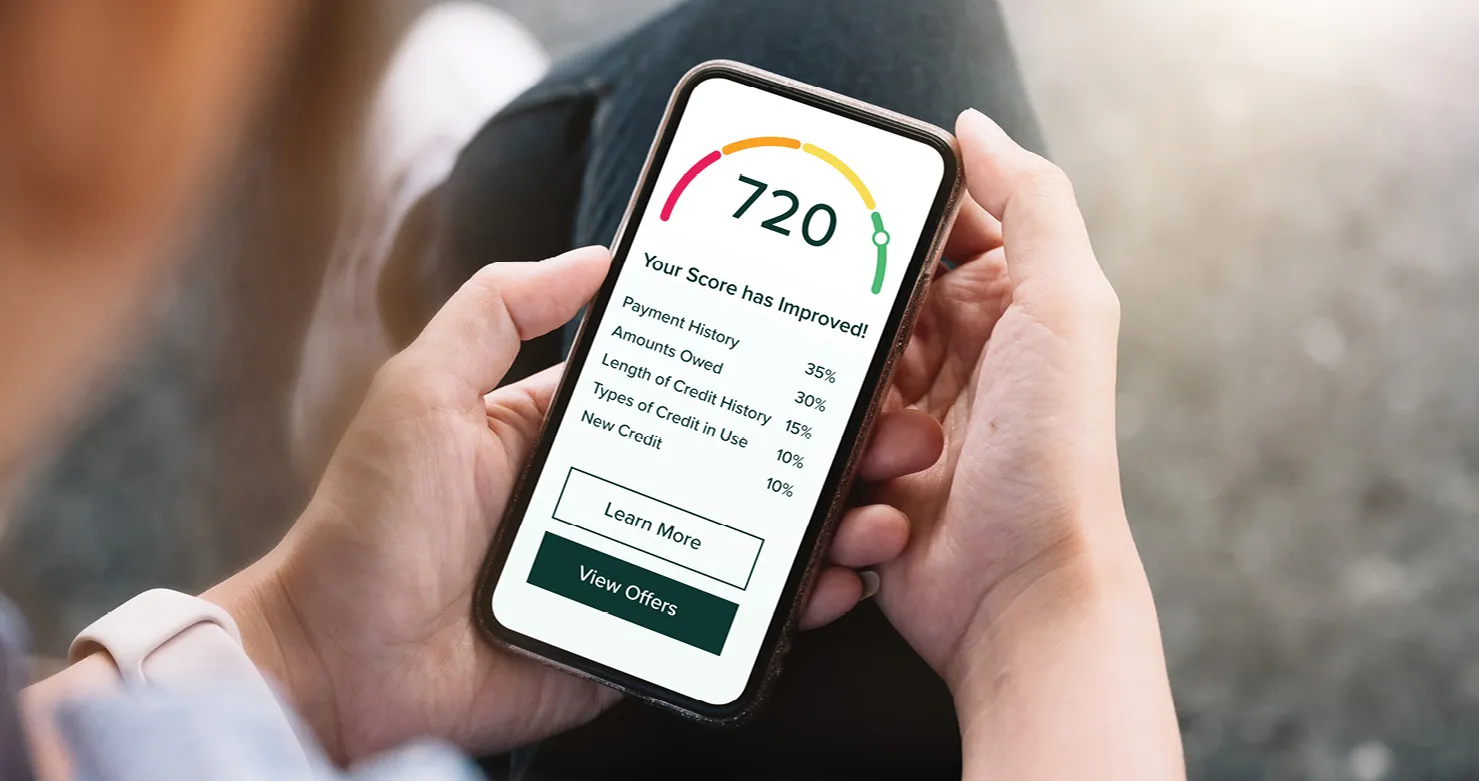
Your credit score is one of the factors lenders consider when evaluating your mortgage application. It can affect:
- Mortgage approval
- Interest rate
- Monthly payment
- Down payment requirements
- Loan program eligibility
- Private Mortgage Insurance (PMI) costs, when applicable
Generally, stronger credit profiles may qualify for more favorable loan terms, although approval always depends on the overall financial picture.
Common Mortgage Programs and Credit Considerations
Different loan programs have different qualification requirements. Programs may include:
Conventional Loans
Often preferred by borrowers with strong credit profiles and stable income. Potential benefits include:
- Competitive interest rates for qualified borrowers
- Flexible loan terms
- Various down payment options
- Primary, second-home, and investment property financing
FHA Loans
Designed to make homeownership more accessible for many buyers. Potential advantages include:
- Lower down payment options for qualified borrowers
- Flexible credit guidelines compared to some conventional loans
- Popular among first-time homebuyers
VA Loans
Available to eligible veterans, active-duty service members, and certain surviving spouses. Potential benefits include:
- No down payment for many qualified borrowers
- No monthly mortgage insurance requirement
- Competitive financing options
Eligibility requirements apply.
USDA Loans
Available for eligible rural properties and qualified borrowers. Potential benefits include:
- No down payment for many qualified borrowers
- Competitive financing
- Reduced upfront costs
Property and income eligibility requirements apply.
Can You Buy a Home With Less-Than-Perfect Credit?
Yes. A lower credit score does not automatically prevent you from purchasing a home. Lenders also evaluate factors such as:
- Employment history
- Income stability
- Debt-to-income ratio
- Available assets
- Down payment
- Cash reserves
- Overall credit history
Every borrower’s situation is unique.
How to Improve Your Credit Before Applying
If you’re planning to buy a home, improving your credit profile may increase your financing options. Helpful strategies include:
- Paying all bills on time
- Reducing credit card balances
- Avoiding new credit accounts before applying
- Reviewing your credit reports for errors
- Keeping existing accounts open when appropriate
- Limiting unnecessary hard credit inquiries
- Paying down outstanding debt
Small improvements may strengthen your overall mortgage application.
Common Credit Mistakes to Avoid
Before closing on a home, avoid:
- Financing a new vehicle
- Opening multiple credit cards
- Missing payments
- Maxing out credit cards
- Co-signing new loans
- Closing long-established credit accounts without understanding the impact
- Making large purchases on credit
These actions can affect your mortgage approval or loan terms.
How Nelson Capital Financial Services Can Help
Our team helps buyers understand their mortgage options based on their complete financial profile—not just a single credit score. We assist with:
- Mortgage pre-approval
- Credit review
- Loan program comparisons
- FHA financing
- VA financing
- Conventional loans
- USDA loans
- Jumbo loans
- ITIN loans
- Bank Statement loans
- Non-QM financing
We’ll work with you to identify financing solutions that align with your goals and qualifications.
Frequently Asked Questions
What is considered a good credit score for buying a home?
There isn’t a single score that guarantees approval. In general, stronger credit profiles may qualify for more loan options and better interest rates, but lenders evaluate your complete financial situation.
Can I buy a home if my credit isn’t perfect?
Yes. Many borrowers qualify for financing despite credit challenges. Eligibility depends on factors such as income, debt, assets, employment history, and the specific loan program.
Does checking my credit hurt my score?
Checking your own credit report generally does not affect your credit score. Mortgage- related lender inquiries made within a limited shopping period are often treated differently by credit scoring models than unrelated inquiries.
Can improving my credit lower my mortgage payment?
Potentially. A stronger credit profile may help qualified borrowers obtain more favorable loan terms, which can affect monthly payments over the life of the loan.
Should I get pre-approved before improving my credit?
Yes. Mortgage pre-approval can help identify your current financing options and highlight areas where improving your credit profile may expand those options.
Start Your Mortgage Pre-Approval Today
Whether your credit is excellent, average, or still improving, Nelson Capital Financial Services is ready to help you understand your options. We’ll review your financial profile, explain available mortgage programs, and guide you through every step of the home-buying process.
Contact Nelson Capital Financial Services
Phone: 407-616-7894
Office Address: 3700 34th Street, Suite 100P Orlando, FL 32805
Schedule your free mortgage consultation today and take the next step toward homeownership.